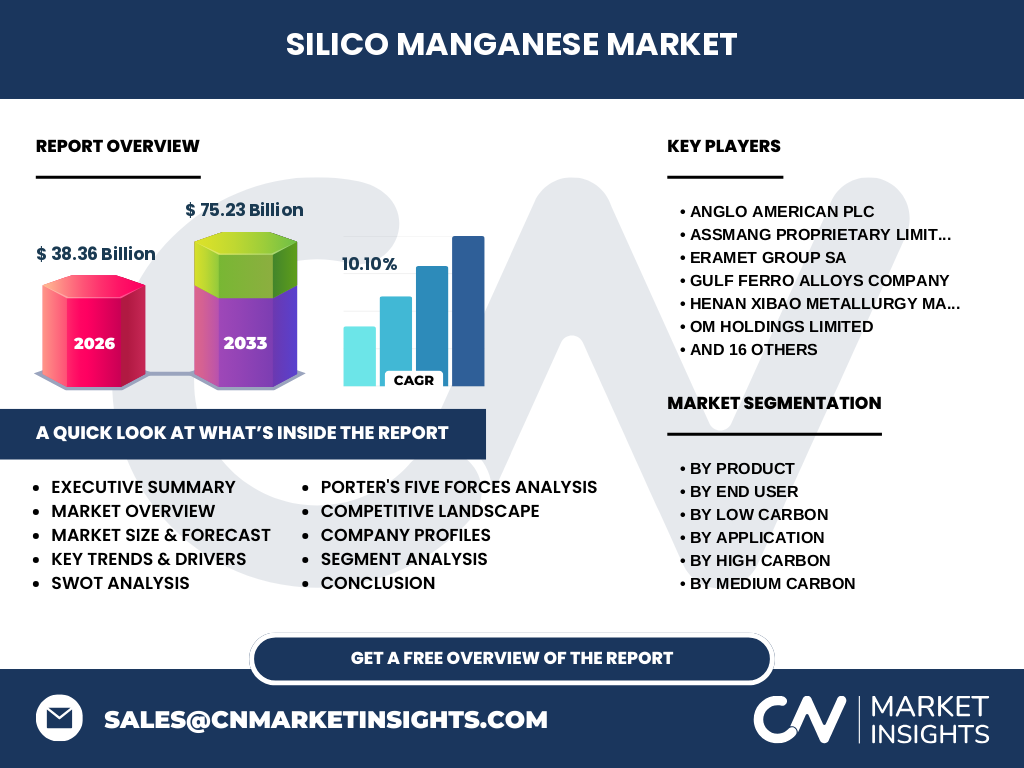
Market overview — definition, scope, and industry significance of Silico Manganese Market
The Silico Manganese Market anchors global metallurgy as a critical deoxidizer and alloying agent. Our analysis indicates a 2026 market size of 38.36 Billion, driven by intense demand for high-performance carbon and stainless steel production across major industrial corridors.
Structural Growth Drivers and Market Restraints
Key market drivers include robust infrastructure investments and rising automotive manufacturing output. Conversely, escalating electricity tariffs and stringent environmental mandates from regulatory bodies restrain production margins, disproportionately impacting energy-intensive smelting operations worldwide.
Emerging Trends and Strategic Growth Patterns
Industry trends reveal a pronounced shift toward low-carbon metallurgy and energy-efficient submerged arc furnaces. Market leaders like Ferroglobe PLC and Eramet Group SA are spearheading sustainable processing technologies to mitigate carbon taxation pressures.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted supply chains and shuttered key ferroalloy smelters. However, the subsequent recovery trajectory has been exceptionally robust, fueled by post-lockdown stimulus packages targeting heavy construction and automotive sectors globally.
Competitive Benchmarking and Market Concentration
Market concentration is moderately fragmented, featuring dominant global players alongside agile regional smelters. Strategic positioning relies heavily on captive raw material access and power cost optimization, distinguishing firms like Tata Steel Limited and OM Holdings Limited.
Executive Summary of the Silico Manganese Market
Our proprietary research projects the Silico Manganese Market to surge from 38.36 Billion in 2026 to 75.23 Billion by 2033, achieving a stellar 10.10% CAGR. This dynamic expansion reflects accelerating steel demand across emerging economies.
Long-Term Market Forecast (2027 to 2033)
Driven by persistent industrialization and stringent metallurgical standards, the market trajectory points toward accelerated expansion. The projected 10.10% CAGR highlights lucrative investment opportunities culminating in a 75.23 Billion valuation by 2033.
Granular Segmentation Analysis
Segmentation spans multiple dimensions: by product (Low Carbon, Medium Carbon, High Carbon); by end-user (Defense, Automotive, Consumer Appliances, Construction); and by application (Carbon Steel, Stainless Steel, Alloy Steel, Cast Iron). High-carbon variants maintain dominant volume shares in bulk carbon steel production.
Geographic Distribution and Regional Performance
Regional performance varies significantly, with Asia-Pacific serving as the primary manufacturing and consumption hub. Localized energy constraints and raw material availability dictate distinct operational hurdles across European, North American, and Asian operational theaters.
In-Depth Regional Review of Production Hubs
Asia-Pacific dominates due to massive steel output in nations like China and India, supported by localized manganese ore reserves. Meanwhile, European markets focus on high-grade specialty alloys, navigating strict carbon border adjustment mechanisms.
Company Profiles and Strategic Positioning
Industry heavyweights such as Steel Authority of India Limited, Anglo American plc, and Assmang Proprietary Limited leverage integrated supply chains. Their strategic focus centers on operational efficiency and expanding low-carbon product portfolios to capture premium margins.
Porter's Five Forces Competitive Assessment
Bargaining power of suppliers remains moderate due to concentrated high-grade manganese ore mining. Threat of substitutes is remarkably low, given that silico manganese remains chemically indispensable for cost-effective steel deoxidation.
SWOT Analysis of the Silico Manganese Sector
Strengths lie in established metallurgical utility and vast raw material reserves. Weaknesses include high electricity dependency. Opportunities emerge in advanced automotive steels, while threats stem from volatile power costs and tightening environmental compliance standards.
Value Chain Analysis from Ore to End-User
The value chain initiates with mining high-grade manganese ore, quartz, and metallurgical coke. Smelting via electric arc furnaces transforms these inputs into alloy grades, which are subsequently distributed via major logistics ports to steel mills and automotive manufacturers.
Investment Insights and High-Potential Areas
Investors should target low-carbon grade production facilities and regions offering subsidized renewable energy for smelting. Companies capable of scaling eco-friendly furnace technologies present superior long-term appreciation potential within this high-growth sector.
Conclusion and Strategic Takeaways
The Silico Manganese Market offers exceptional growth prospects, backed by a projected 75.23 Billion valuation by 2033. Stakeholders must prioritize energy efficiency and regulatory compliance to capitalize on robust steel industry demand.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining global trade registry data, primary executive interviews with smelter operators, and secondary macroeconomic indicators from international steel associations to ensure absolute market accuracy.
Scope of the Report and Coverage Parameters
This report encompasses comprehensive global analysis across specified product grades, applications, and end-user verticals from 2026 through 2033. Geographical coverage spans all major producing and consuming nations, evaluating both macroeconomic and microeconomic industry variables.
Recent Developments and Industry Innovations
Recent strategic moves include capacity expansions by Pertama Ferroalloys Sdn. Bhd. and technological partnerships focused on waste-heat recovery systems. These initiatives underscore the sector's commitment to lowering carbon intensity while meeting escalating global steel demand.